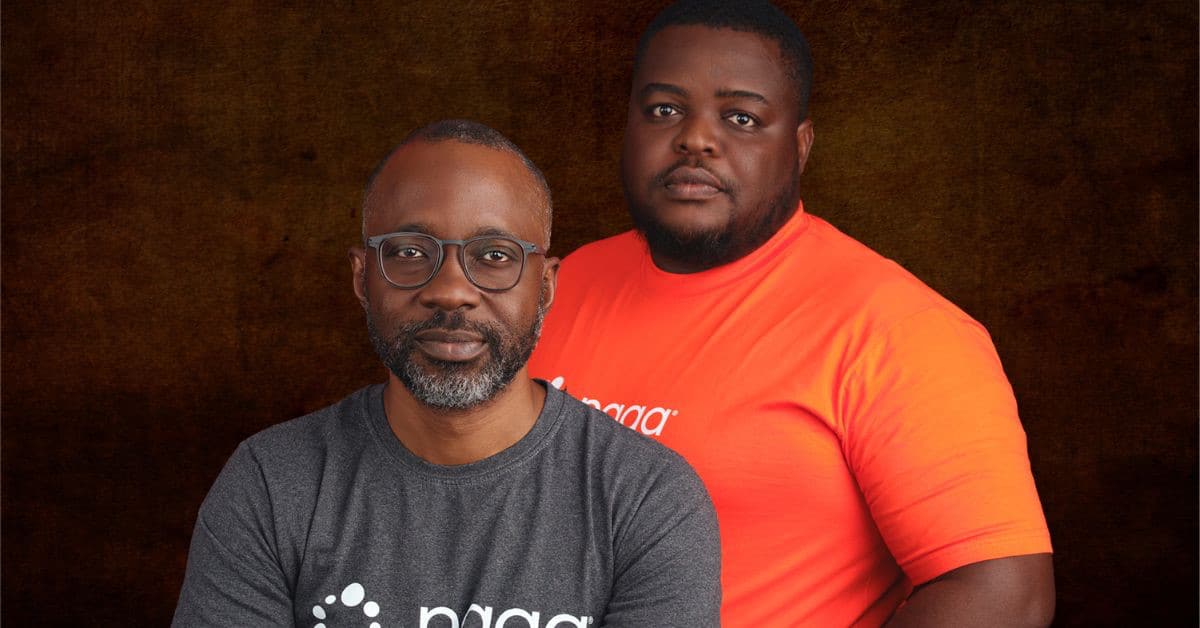
Stablecoins in Africa are attracting growing attention, but making them part of everyday financial transactions will take more than the efforts of a single fintech company. That was the position shared by Paga Group CEO Tayo Oviosu during a discussion at Moonshot by TechCabal in Lagos.
The conversation brought together industry representatives from Paga, Flutterwave, Juicyway and Breet to examine how digital currencies could shape the future of payments across the continent. Their discussion reflects a growing belief in the industry that no single firm can build everything stablecoins need to work at scale.
Stablecoins are digital currencies designed to maintain a relatively stable value, usually by being linked to traditional currencies such as the US dollar. Unlike more volatile cryptocurrencies, they aim to give users a reliable way to store and move value. Their ability to make cross-border transactions faster has made them increasingly attractive to businesses and individuals dealing with international payments.
For many Africans, this matters in practical ways. Sending money across borders can be slow and costly through traditional channels, and businesses that import goods or pay suppliers abroad often face delays and fees. A dollar-linked digital asset can, in principle, shorten that process and make costs easier to predict. This is why interest in stablecoins in Africa has continued to grow among fintech companies, startups and everyday users.
However, wider adoption still faces real challenges. Although stablecoins can make international transfers faster and potentially cheaper, their usefulness depends on whether people can easily access and spend them. Many consumers still rely on traditional banking channels when converting digital assets into local currencies or using their funds for everyday purchases. If that conversion process is difficult or unreliable, the speed advantage of a stablecoin is quickly lost.
Liquidity is another concern. For stablecoins to work smoothly, users need to be able to move between digital assets and local currencies without long delays or unpredictable pricing. That requires strong relationships between payment providers, banks and other institutions, and it is difficult for any one company to build alone.
Regulatory uncertainty adds to the complexity, particularly around how digital currency transactions are monitored and governed. Businesses and consumers are more likely to trust a product when the rules are clear and the providers are accountable. Without that clarity, even the most convenient service may struggle to win lasting confidence.
Oviosu’s position highlights the need for cooperation among payment providers, financial institutions, regulators and businesses. Different companies will need to address various parts of the ecosystem, from payment infrastructure and liquidity to compliance and consumer access. In this view, the future of stablecoins in Africa depends less on one dominant player and more on a network of partners, each solving a different piece of the puzzle.
This collaborative approach mirrors a wider trend across the continent’s technology sector, where partnerships are increasingly seen as the quickest route to scale. A recent example is how FCMB and Mastercard are using technology to connect Nigerian farmers with funding and new markets, showing how banks and technology firms can combine strengths to reach people who were previously underserved.
For African businesses, a more connected stablecoin ecosystem could create additional opportunities for international payments and cross-border trade. Companies that trade across borders could benefit from faster settlement and clearer pricing, while smaller businesses may gain access to payment options that were once out of reach. At the same time, the financial sector is not the only one racing to adapt, as seen in Enza Capital’s new fund to back Africa’s artificial intelligence startups.
Still, building trust and ensuring regulatory clarity will be essential. Users need to feel confident that their funds are safe, that they can convert them when needed, and that the companies handling them operate within clear rules. Education will also play a part, since many people are still learning what stablecoins are and how they differ from other digital assets.
As stablecoins continue to attract attention, the next stage of development will depend on whether the industry can make them practical, accessible and reliable for everyday users. If fintech companies, financial institutions and regulators can work together, stablecoins in Africa could move from a topic of discussion to a regular part of how people and businesses move money.