Tap-to-pay in Nigeria is getting a major push as Interswitch expands contactless payment infrastructure through partnerships with five Nigerian banks. The initiative aims to make contactless payments more accessible to consumers and businesses, reducing the need to swipe cards during everyday transactions.
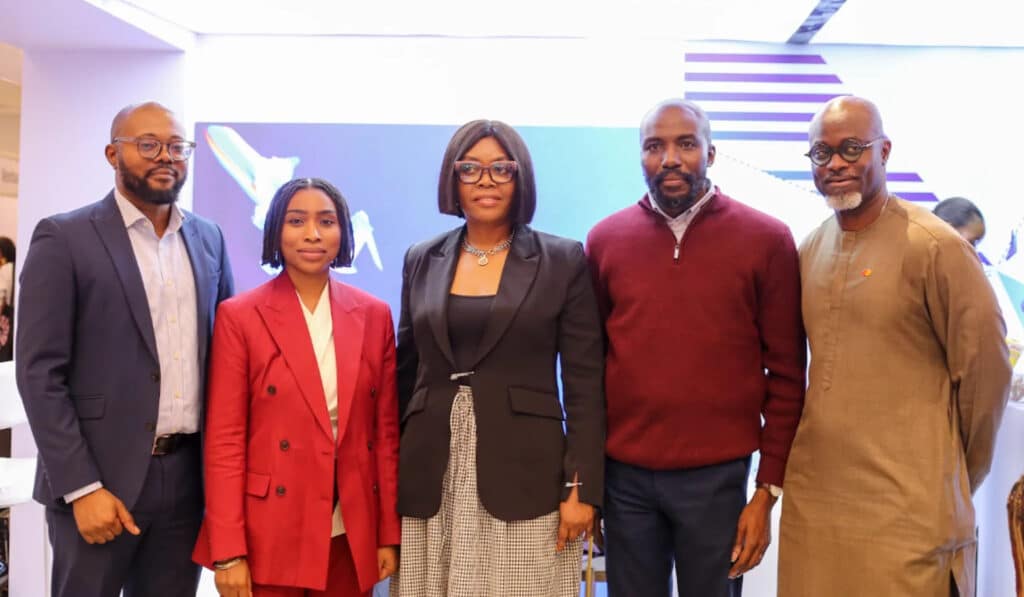
Interswitch announced on October 19 that it was helping financial institutions build the infrastructure needed to support tokenised payments. On October 26, the company announced partnerships with five Nigerian banks: GTBank, Wema Bank, Providus Bank, Zenith Bank and FirstBank. The payment technology company is also working with card schemes and merchants to support the adoption of tokenised payments. Together, these partners are laying the groundwork for tap-to-pay in Nigeria to become an everyday way to pay.
Each of the five banks brings its own customers to the initiative, which could help bring contactless payments to more Nigerians as their cards and devices are supported. Swiping or inserting a card has long been the standard way to pay at a terminal, and tap-to-pay offers an alternative that asks for fewer steps.
Tap-to-pay lets customers make payments by bringing a compatible contactless card or device close to a payment terminal. Instead of inserting or swiping a card, the customer completes the transaction through contactless technology. The same infrastructure can also support digital wallets and, where available, payments through compatible smartphones and wearable devices. As more financial institutions adopt it, tap-to-pay in Nigeria could become an additional option for customers who want faster ways to complete transactions.
Behind the process is payment tokenisation. Rather than sending the customer’s original card number during every transaction, the system uses a substitute digital identifier known as a token. This helps limit the exposure of sensitive payment information and can make certain forms of payment fraud more difficult. Customers can complete eligible transactions without repeatedly exposing their actual card details, which gives people who rely on electronic payments another option. For businesses and consumers who depend more and more on electronic payments, that added layer of protection matters.
For merchants, contactless payments could mean quicker checkout and more ways for customers to pay. Businesses that adopt compatible terminals may also be better positioned to serve shoppers who prefer to tap instead of swipe. The expansion of tap-to-pay in Nigeria could also encourage more merchants to adopt modern payment infrastructure, which in turn supports the growth of digital payments in Nigeria.
However, the success of tap-to-pay in Nigeria will depend on how widely the service becomes available. Three things need to line up:
- Banks must support the technology.
- Merchants need compatible payment terminals.
- Customers must have eligible cards or devices.
Wider adoption will require cooperation between banks, payment companies, merchants and technology providers. If one link in that chain is missing, customers may find the service works in some places but not others. For everyday customers, the real benefit will depend on whether the service is easy to access and use in ordinary situations. Customers who want to try it should ask their bank whether their card or device is eligible and look for merchants with compatible terminals.
Interswitch’s latest move reflects growing competition among payment providers to improve how Nigerians make digital transactions. As electronic payments become more important to businesses and consumers, providers are looking for ways to make payments more convenient while keeping them secure. The same push is visible elsewhere in African fintech, as Paga’s CEO recently outlined the hurdles to stablecoin adoption in Africa.
Interswitch’s partnerships with GTBank, Wema Bank, Providus Bank, Zenith Bank and FirstBank mark another step towards expanding contactless payment options in the country. Their long-term impact will depend on how quickly the supporting infrastructure reaches businesses and customers. For now, the partnerships signal where contactless payments in Nigeria are heading, and the next test is how quickly customers and merchants can actually use them.
.